Starting November 20, 2026, new rules will apply to consumer loans. Through the implementation act concerning the Directive (EU) 2023/2225 on Consumer Credit Agreements and Regulating the Promotion of Climate-Neutral Mobility, the German legislature has transposed the new requirements of the Second Consumer Credit Directive (CCD2) into national law. The new rules bring numerous changes, though these do not affect only banks that issue consumer loans. To address recent developments in the area of small loans and payment deferrals—and the associated new risks for consumers—the rules also extend, in particular, to entities that are not regulated credit institutions or payment institutions. As a result, even unregulated companies operating in the retail sector will have to consider whether the new rules impose new requirements on their business models. The legislature has placed particular emphasis on so-called “Buy Now, Pay Later” (BNPL) offers, which allow consumers to purchase goods or services and pay for them at a later date. Under current law, there are exceptions for consumer loans of less than 200 euros, for those with a term of up to three months, and for BNPL, which exclude these forms of credit from the scope of consumer credit contract law. However, this will no longer be the case as of November 20, 2026.
Companies Will Be Required to Comply with the New Consumer Credit Law in the Future?
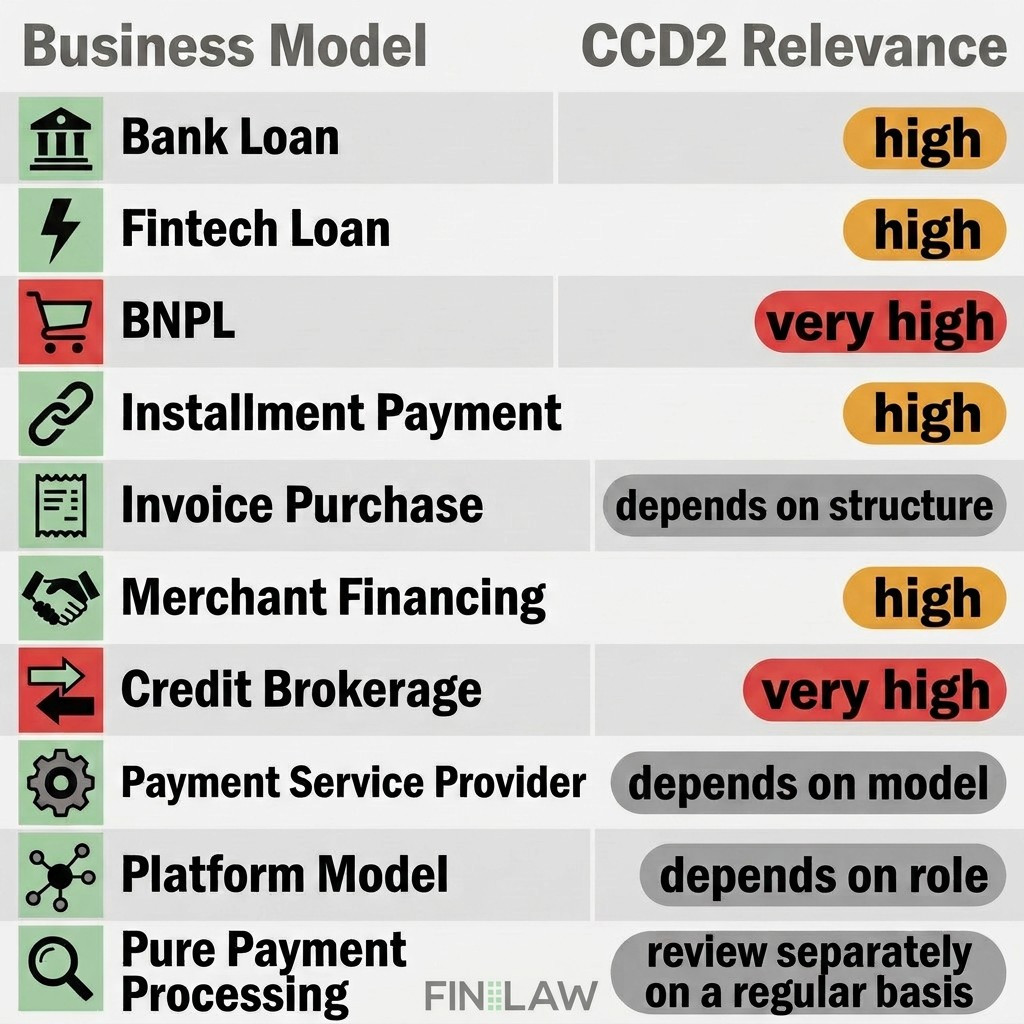
The new rules naturally apply to banks active in the lending business that extend credit to consumers. Payment institutions that are permitted to grant credit on a limited basis under their regulatory licenses—for example, by granting a line of credit in connection with payment services—should also expect to comply with the stricter consumer protection rules under CCD2. A particularly significant change is that, due to the elimination of sector-specific exemptions for microloans, short-term loans, and BNPL models, even unregulated retail companies may increasingly be affected by the provisions of the new consumer credit law, depending on the structure of their payment terms for consumer customers. This is because the new rules may also apply, for example, to certain arrangements involving sales financing, deferred payment of the purchase price, or installment payment agreements. The following overview shows which business models may be specifically affected and to what extent:
What Changes Will There Be for Companies Affected by CCD2?
Companies subject to the new regulations under consumer credit law must comply with numerous new obligations. Of particular relevance are the stricter requirements for fulfilling pre-contractual information obligations, which the legislature has revised for contracts to be concluded on the 20 of November, 2026, or later. The new list of pre-contractual information obligations for consumer loan agreements, financing assistance agreements, and loan brokerage agreements comprises a total of 28 items of information that businesses must provide to consumers. This includes, among other things, information about the business and the terms of the contract—in particular, the term, interest rates, late payment interest, and the annual percentage rate (APR)—as well as due dates, any provisions regarding prepayment penalties, and the total costs to the consumer. In addition, a representative example illustrating the total amount and the annual percentage rate (APR)—including the underlying assumptions—as well as a repayment schedule must be provided. Specific warnings regarding the consequences of failing to comply with contractual obligations must also be provided. Of particular relevance to companies that have not been regulated to date is the introduction of a mandatory registration requirement for lenders under the new Sales Financing Supervision Act (AbsFinAG) with BaFin as the competent supervisory authority. Companies subject to this registration requirement will also have to meet additional requirements when designing their employee compensation systems, particularly with regard to avoiding inappropriate incentives through performance targets. In addition, consumer credit lenders will be required to conduct a creditworthiness check before entering into a loan agreement, and the result of this check must be positive.
What Should Companies with Consumer Customers Do by November 20, 2026?
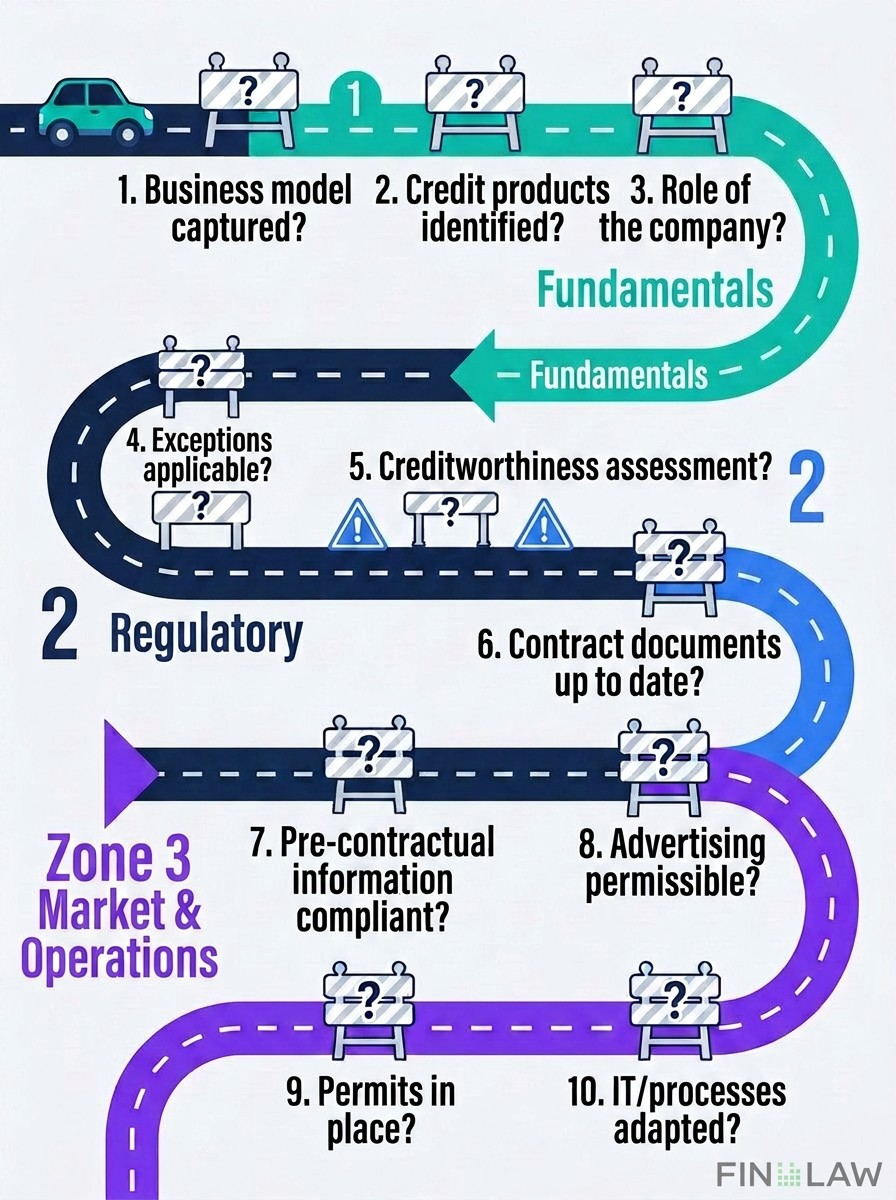
The requirements for unregulated companies with consumer customers will change significantly with the implementation of the CCD2 requirements into German law as of November 20, 2026. Affected companies are therefore advised to have their business models—and, in particular, their sales processes—thoroughly reviewed in light of the new requirements under consumer credit law. The following list of questions may provide some initial guidance:
Attorney Dr. Lutz Auffenberg, LL.M. (London)
subscribe to Newsletter-
 FIN LAW – Awarded by WiWo for the Third Time
For the third time, WirtschaftsWoche (WiWO) magazine has awarded FIN LAW and Dr. Lutz Auffenberg, LL.M. (London) as a top Law Firm and Lawyer respectively.
-
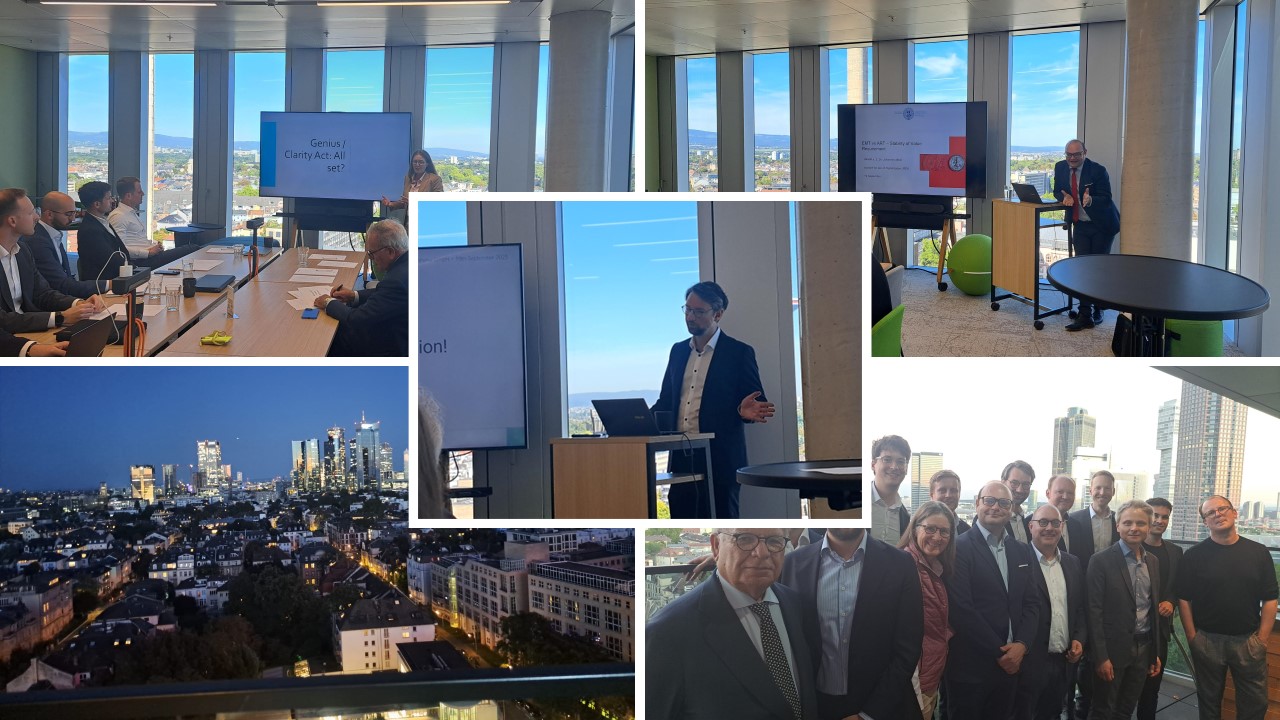 FIN LAW Hosts the Annual Meeting of the Fintech Legal Network
FIN LAW had the pleasure of hosting the Annual Meeting of the Fintech Legal Network and was pleased to welcome members to its offices in Senckenberganlage.
-
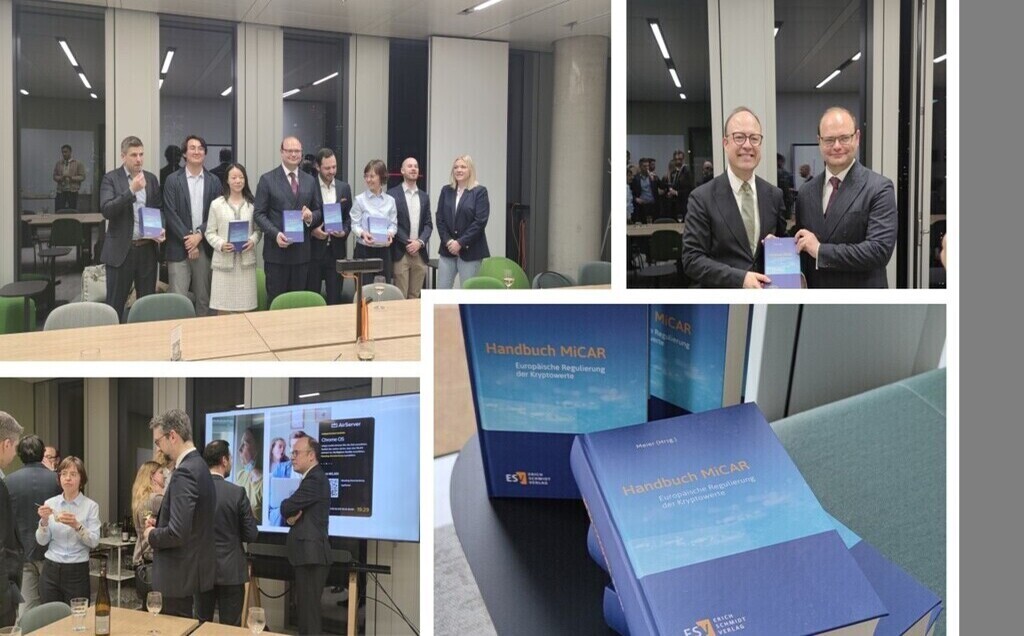 Successful Book Launch at FIN LAW for the New MiCAR Handbook by Dr. Johannes Meier
Presentation of the new MiCAR handbook by Dr. Johannes Meier at the book launch event of FIN LAW.